20/10/2026
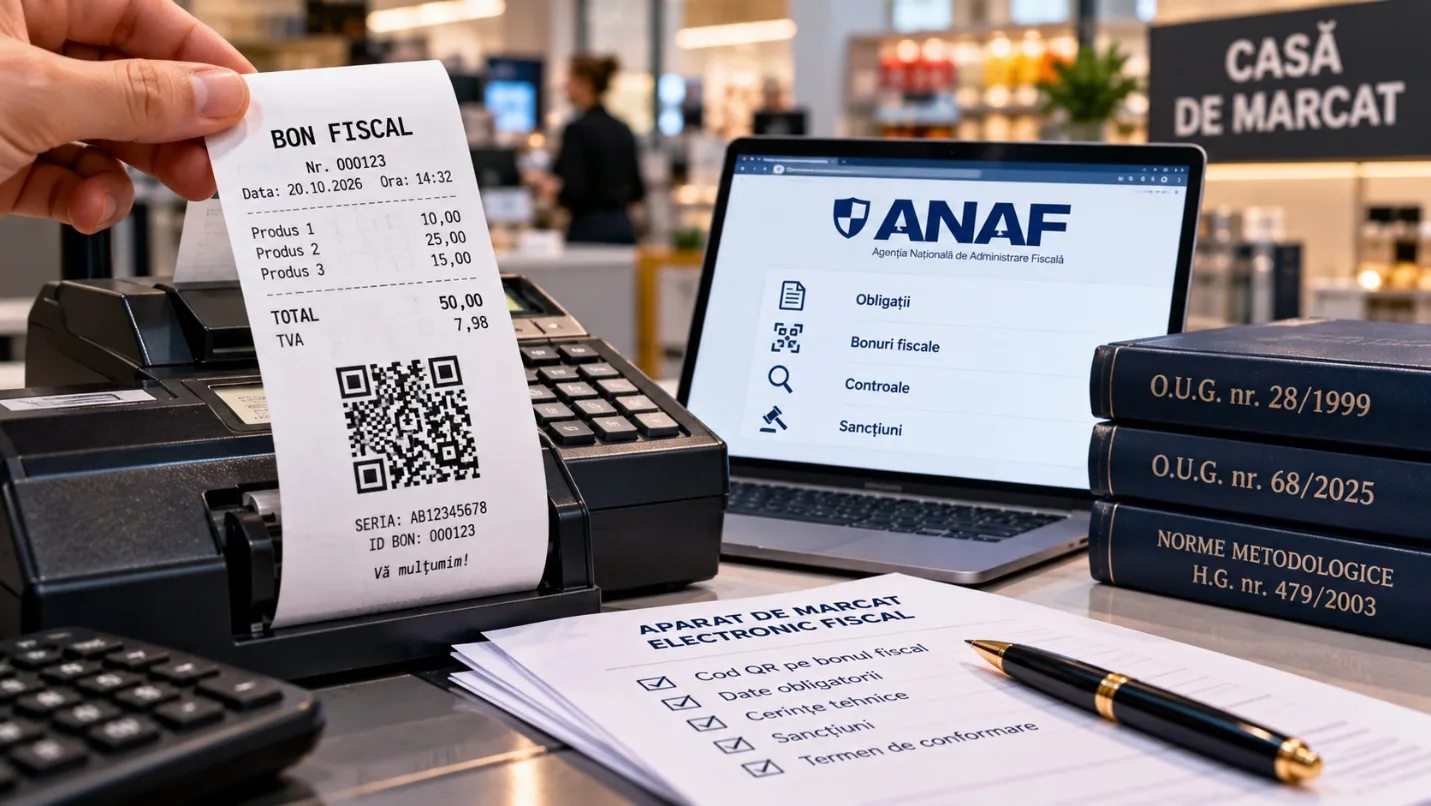
Hundreds of thousands of businesses face uncertainty over the implementation of QR codes on fiscal receipts, as the date until which the application of penalties is suspended draws near, while the technical requirements needed for implementation have not yet been laid down through an amendment of the implementing rules.
Although the obligation to print certain information in the form of a QR code is laid down by the legislation in force, the Chamber of Tax Consultants has informed the Ministry of Finance that the electronic fiscal cash registers available on the market cannot issue, in the form required by law, QR codes containing all the required data. In this context, the professional body has requested official clarification and a legislative solution that would avoid penalising businesses for a non-compliance they are unable to remedy in practice.
For businesses, the issue must be examined from two distinct perspectives: the legal obligation to issue fiscal receipts with a QR code and the applicability of penalties in the absence of the technical framework needed for compliance.
The QR code rules were introduced by the 2024 amendments to Government Emergency Ordinance No 28/1999 on the obligation of businesses to use electronic fiscal cash registers.
Under Article 4(2¹) of GEO No 28/1999, the date and time of issue of the fiscal receipt, the receipt's identification number and the fiscal serial number of the electronic fiscal cash register must also be printed on the receipt in the form of a QR code.
In addition, Article 4(2) regulates other information that must appear on fiscal receipts issued by the devices provided for by law, including the unit of measurement, the customer's tax identification code, at the customer's request, and the receipt's identification number.
The legal framework therefore lays down specific obligations regarding the content of the fiscal receipt, and the QR code is an additional means of displaying certain information needed to identify and verify the document.
Although the obligation is laid down by law, putting it into practice requires clear technical requirements that allow manufacturers and authorised distributors to adapt electronic fiscal cash registers.
Without sufficiently precise technical specifications, implementation cannot be carried out in a uniform and verifiable manner.
The elements requiring clarification include:
According to information published by the Chamber of Tax Consultants, the implementing rules of GEO No 28/1999, approved by Government Decision No 479/2003, had not been amended as required for the implementation of the QR code at the time the letter was sent to the Ministry of Finance on 12 October 2026.
In these circumstances, the National Institute for Research and Development in Informatics – ICI Bucharest cannot issue a favourable supplementary technical approval for an implementation whose technical benchmark has not yet been established by secondary legislation.
In this context, the Chamber of Tax Consultants has argued that no electronic fiscal cash register on the market issues receipts containing all the required data in the QR format provided for by the rules.
The problem is therefore not merely whether a simple software update is available. The official technical framework must first be established, followed by the adaptation of the solutions by authorised distributors and completion of the applicable testing and approval procedures.
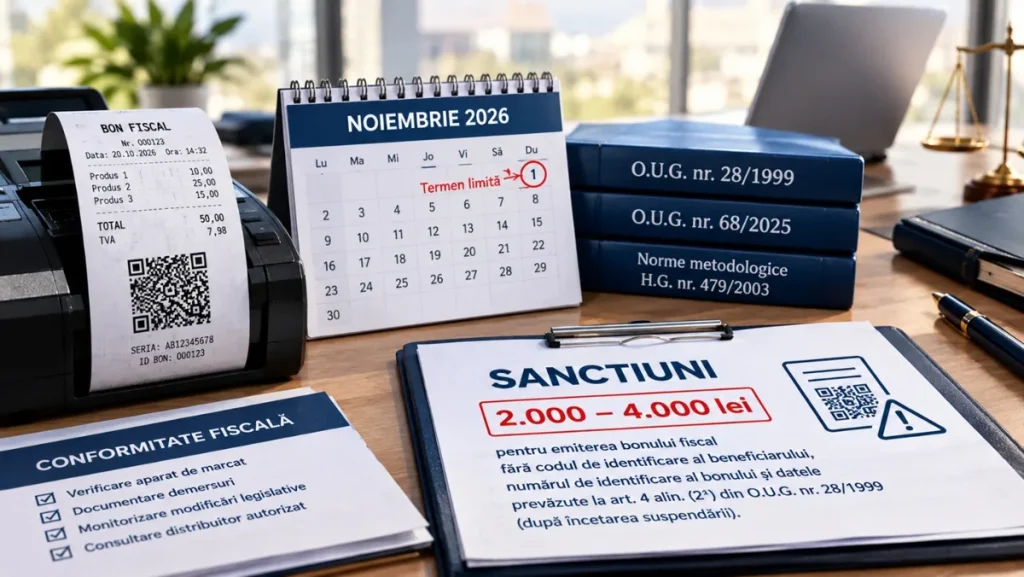
Under Article IV of GEO No 68/2025, published in Official Gazette No 1132 of 8 December 2025, the application of Article 10(f) and Article 11(1)(h) of GEO No 28/1999 was suspended until 1 November 2026 for cases where the fiscal receipt is issued without the customer's identification code, the receipt's identification number and the data that must be displayed in the form of a QR code under Article 4(2¹).
The measure was adopted precisely because businesses risked being penalised even though they did not have the conditions needed to comply with the technical requirements.
From a legal point of view, an essential distinction must be made: GEO No 68/2025 did not abolish the QR code obligation, but suspended the application of penalties for the situation expressly provided for in the act, until the set date.
In the absence of further legislative action, the end of the suspension on 1 November 2026 may bring back into play the penalty regime laid down by GEO No 28/1999 for this non-compliance.
At the time of writing, the Chamber of Tax Consultants had already asked the Ministry of Finance for an official position, but the public information consulted did not indicate that any new measure extending the suspension had been adopted.
Under Article 10(f) of GEO No 28/1999, issuing a fiscal receipt with incorrect data, other than in situations separately regulated by law, or without all the data provided for in Article 4(1), (2) and (2¹) constitutes a minor offence.
For this offence, Article 11(1)(h) provides for a fine of between RON 2,000 and RON 4,000.
The application of these provisions to the absence of the QR code is suspended under the conditions and until the date provided for in Article IV of GEO No 68/2025. Consequently, in the absence of an extension of the suspension or other legislative action, businesses may face the risk of the statutory penalty being applied from 1 November 2026.
It should be stressed that the suspension concerns the situation expressly regulated and is not a general suspension of the obligations relating to the issue of fiscal receipts. The other obligations applicable to electronic fiscal cash registers remain subject to the relevant legal regime.
The current situation raises a relevant legal issue: how can a business be penalised for failing to fulfil an obligation if the necessary technical solution cannot actually be implemented in the absence of official requirements?
On the one hand, the obligation to issue fiscal receipts containing the elements required by GEO No 28/1999 is laid down by law. On the other hand, the actual implementation of the QR code depends on factors outside the retailer's direct control: the adoption of technical requirements, the adaptation of the devices and the obtaining of the necessary approvals.
This situation should not automatically be interpreted as an exemption from liability for every business. Neither the lack of technical rules nor the difficulties faced by distributors amount, in themselves, to the removal of the legal obligation.
Nevertheless, the objective impossibility of compliance, caused by the lack of the necessary technical framework, is an important factor that the authorities must take into account when considering whether to penalise businesses.
In the event of an inspection, documents showing the steps taken by the company to comply may be relevant to the assessment of the specific situation. However, the legal effect of such documents must be assessed in light of the circumstances of the case and the applicable rules, without assuming that they automatically remove liability for the minor offence.
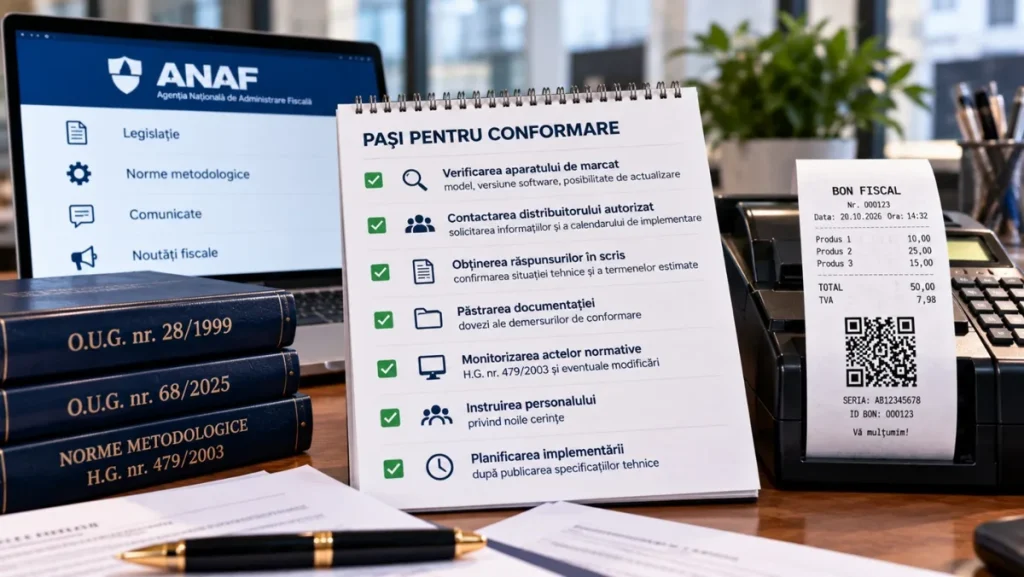
Until the legislative and technical framework is clarified, companies using electronic fiscal cash registers should adopt preventive measures, even if the QR code cannot currently be implemented in the required form.
First, it is recommended to contact the authorised distributor or the accredited service unit to check the technical status of the device used, the possibility of adapting it and the stage of the approval procedures.
Second, companies should request and keep the replies received in writing, including information on the technical impossibility of implementation, the lack of official specifications or the estimated timeframes for updating the equipment.
It is also useful to keep the relevant technical documentation for the devices used, information on the models and software versions, and evidence of the requests made to the distributor.
Businesses should not implement unofficial technical modifications or use makeshift solutions to generate QR codes. Compliance must be achieved through solutions compatible with the legal requirements and the authorisation regime applicable to electronic fiscal cash registers.
The situation calls for swift and coherent action by the competent authorities.
First, the implementing rules approved by Government Decision No 479/2003 must be amended and supplemented so as to set out clearly the technical requirements for generating and printing the QR code.
Second, sufficient time must be allowed for adapting the software, testing the cash registers and obtaining the corresponding technical approvals.
Third, given that the 1 November 2026 deadline is approaching, the authorities should consider adopting a transitional legislative measure allowing effective compliance once the technical specifications have been published.
Any extension of the suspension of penalties should be linked to a realistic implementation timetable, so that businesses are not held liable for a minor offence in respect of a non-compliance that cannot be remedied by the means at their disposal.
In the immediate future, businesses must treat the QR code issue as an evolving tax compliance matter.
Each company is advised to check the status of its own cash registers, request information from the authorised distributor, keep the relevant documents and follow any legislative changes.
At the same time, companies must avoid concluding that the lack of technical rules in itself removes the statutory obligation or the risk of penalties once the suspension expires.
The implementation of the QR code on fiscal receipts highlights a lack of alignment between the legal obligation, the necessary technical rules and businesses' actual ability to comply.
Although the obligation to print data in the form of a QR code is laid down by GEO No 28/1999, its practical application requires official technical requirements and certified solutions. Without them, businesses face uncertainty, given that the suspension of penalties is scheduled to end on 1 November 2026.
For companies, the priority is to check their technical situation and document their compliance efforts. For the authorities, the priority is to clarify the technical framework and avoid a penalty regime that could affect businesses that lack the means needed to meet the requirements imposed.
Author: SZ.I.
Copyright © 2026. All rights reserved.
