21/05/2026
Quick summary (updated 13 October 2026): Since 9 March 2026, the sale of an SRL or the withdrawal of a shareholder can no longer be completed without tax clearance from the National Agency for Fiscal Administration (ANAF). GEO No 13/2026 introduced an integrated ONRC–ANAF mechanism under which every transfer of shares is checked for tax purposes before registration, and Order No 1.137/2026 of the President of ANAF and No 1.967/C/2026 of the Minister of Justice, published in Official Gazette No 855 of 12 October 2026, lays down the detailed procedure: a standard notification form, a tax clearance certificate issued within 3 working days, security accepted only in the form of deposited funds or a letter of guarantee/surety insurance policy, and a mandatory 60-day period for settling the debts. This article explains the new procedure step by step and the pitfalls to avoid.
under strict tax control in 2026?
If you manage an SRL and plan to sell the company, to withdraw from the shareholding or to bring in a new shareholder by transferring shares, 2026 marks a structural change in the rules. The transfer of shares is no longer a private legal act between transferor and transferee, completed by a simple filing with the National Trade Register Office (ONRC). It has become an operation subject to a double control - legal at ONRC and fiscal at ANAF - through integrated verification mechanisms.
Through this reform, the Romanian State pursued two clear objectives:
1. Putting a stop to the phenomenon of "selling companies with tax debts" - a practice whereby entrepreneurs who left behind unpaid obligations to the State budget escaped liability by formally transferring the SRL to nominees or fictitious persons.
2. Protecting creditors and contractual partners - who, until 2026, often discovered after takeover that the company had hidden debts or that the former director had disappeared without trace.
The legal basis of the new procedure consists of three successive legislative acts:
1. Law no. 239/2025 on certain measures for the recovery and more efficient use of public resources (the second fiscal package), published in Official Gazette no. 1160/December 2025, in force from 18 December 2025. Article V of this law introduced, for the first time, the obligation to notify ANAF in the case of a transfer of shares.
2. Emergency Ordinance no. 13/2026, published in Official Gazette no. 181 of 9 March 2026, which, through Article I, amends Article V of Law no. 239/2025 and formalises ONRC's role in automatically requesting the Tax Clearance Certificate from ANAF.
3. Order No 1.137/2026 of the President of ANAF and No 1.967/C/2026 of the Minister of Justice approving the Procedure for applying Article V of Law No 239/2025, published in the Official Gazette, Part I, No 855 of 12 October 2026. The Order approves the procedure itself, the model form “Notification of the transfer of shares held by a shareholder of a limited liability company” and the special model tax clearance certificate, and sets out the framework for cooperation between ANAF and the ONRC.
the former and the current regime
The former regime (until 18 December 2025)
Under the regime of the Company Law (Law no. 31/1990), transferring shares to a third party essentially followed these steps:
– The resolution of the General Meeting of Shareholders (GMS) or the decision of the sole shareholder approving the transfer;
– Conclusion of the transfer agreement between transferor and transferee;
– Updating the Articles of Association;
– Filing the application with ONRC;
– Registering the filing and making it enforceable against third parties.
ANAF did not intervene in this process. A company with tax debts could be sold without the tax authority being notified and without the operation being blocked.
The current regime (from 9 March 2026, with the procedure approved by Order No 1.137/1.967/C/2026)
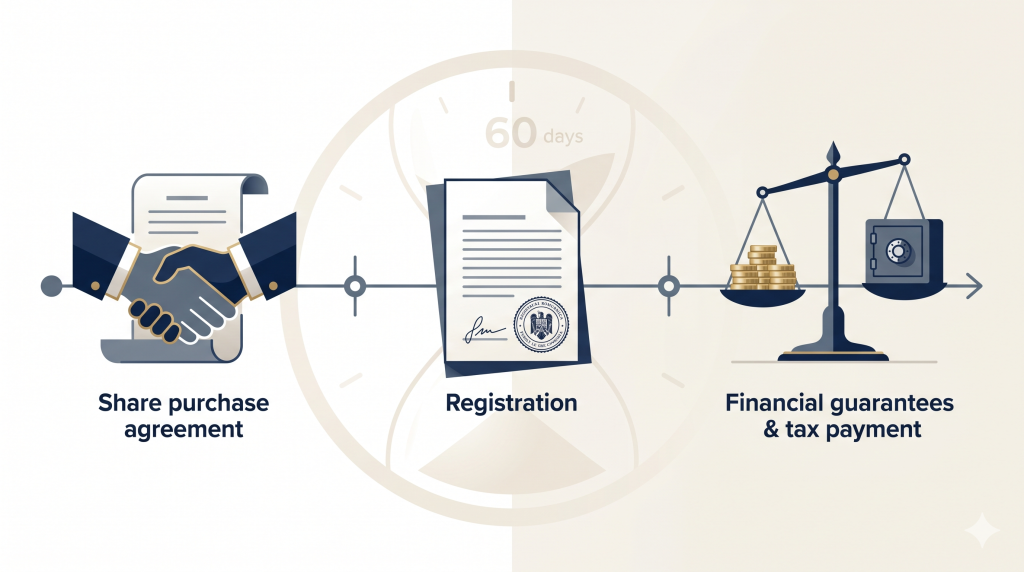
Under Law No 239/2025, as amended by GEO No 13/2026, a transfer of shares is not enforceable against the central tax authority unless the following conditions are met cumulatively:
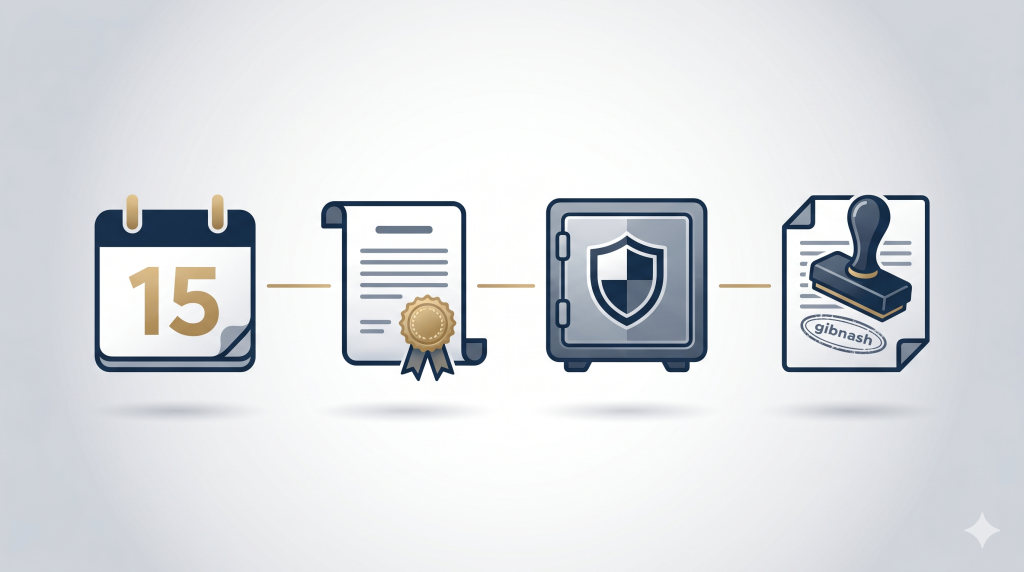
– Notification to ANAF within 15 days of the date of the transfer, on the standard form approved by the Order, accompanied by the instrument of transfer and the updated articles of association;
– Issue of the company's tax clearance certificate (CAF) — issued by ANAF within 3 working days of the notification and also requested by the ONRC upon registration;
– Provision of security for the outstanding tax/budgetary liabilities shown in the CAF (if any), in the form of deposited funds or a letter of guarantee/surety insurance policy;
– The actual registration of the filing at ONRC, following the tax check.
Important: before GEO 13/2026, the restriction applied only to a transfer carried out by the shareholder who held control of the company. From 9 March 2026, the rule is generalised — all transfers are subject to the tax check, regardless of the transferor's percentage holding.
Step 1: Preliminary legal and tax analysis
Before any document is drawn up, it is essential to verify:
– The company's actual tax situation — debts to ANAF, any seizures, garnishments or other precautionary measures;
– The existence of pending litigation that could affect the value of the shares;
– The compliance of the Articles of Association with the legislation in force (in particular the minimum share-capital threshold — see our earlier article on increasing the share capital of an SRL);
– Whether there are pre-emption clauses or restrictions on admitting a new shareholder;
– The director's mandate — if it has expired or is unlimited, it must be regularised before the transfer.
The firm's recommendation: this analysis is vital for the buyer (transferee), but also for the seller (transferor). A proper legal and tax audit identifies hidden risks and allows a genuine price for the shares to be negotiated.
Step 2: Preliminary check of the company's tax position
Following the entry into force of Order No 1.137/1.967/C/2026, the “official” tax clearance certificate for the transfer is issued only after ANAF has been notified, that is, after the contract has been signed. The tax check must therefore be carried out before signing, on the basis of the data available in the SPV (ANAF's Virtual Private Space) — the taxpayer's summary statement or an ordinary tax clearance certificate requested by the company.
The reasons are strictly practical:
– It allows informed negotiation between transferor and transferee regarding any tax debts and their reflection in the price;
– It identifies early the need to provide security, which requires financial planning (available funds or a bank letter of guarantee);
– It avoids surprises — the CAF issued for the transfer covers not only outstanding tax liabilities but also other budgetary claims established in enforceable titles held by ANAF for recovery (for example, fines or other claims sent for enforcement).
Step 3: Adopting the GMS resolution or the sole shareholder's decision
The transfer of shares is an amendment to the Articles of Association and therefore falls within the exclusive competence of the Extraordinary General Meeting of Shareholders. The resolution must necessarily set out:
– Identification of the shares being transferred (number and nominal value);
– The identity of the transferor and the transferee;
– The transfer price and the method of payment;
– Approval of the admission of the new shareholder (if the transferee is a third party);
– Express mention of the notification of ANAF within 15 days;
– Updating of the share structure and of the Articles of Association.
If the company has a single shareholder, a Decision of the Sole Shareholder with the same content is issued.
Step 4: Concluding the transfer agreement
The transfer agreement is the legal instrument by which the transferor transfers ownership of the shares to the transferee. Written form is mandatory. We recommend notarisation in order to:
– Confer a certain date;
– Verify the identity and capacity of the parties;
– Protect the transferee against subsequent claims by the transferor.
In addition to the identification details, the contract must contain representations and warranties from the transferor regarding the company's tax, accounting and legal position — clauses that are essential for the transferee's protection. We also recommend a clause specifying who provides the security required by ANAF and who bears the risk of its enforcement.
Step 5: Notifying ANAF within 15 days, on the standard form
Under Article V of Law No 239/2025 and Article 3 of the Procedure approved by Order No 1.137/1.967/C/2026, the notification must be filed with ANAF within 15 days of the date of the transfer, with the competent central tax authority. The notification is mandatory and may be filed by any of the following:
– The company, through its legal representative;
– The transferor (the shareholder transferring the shares);
– The transferee (the buyer / new shareholder).
The form “Notification of the transfer of shares held by a shareholder of a limited liability company” (Annex 2 to the Order) must be used, and it is filed in one of the following ways:
– at the tax authority's registry office;
– by post, with acknowledgement of receipt;
– through the “Virtual Private Space” (SPV) service.
The notification must be accompanied by:
– the instrument of transfer of the shares (the transfer agreement);
– the updated articles of association, showing the structure of the share capital after the transfer;
– proof of the signatory's capacity (ONRC certificate/extract, authorisation or power of attorney, as the case may be);
– a copy of the identity document, for natural persons.
The same form is used to request the issue of the tax clearance certificate and, if there are debts, ANAF's consent to the provision of security. If the documents are incomplete or unclear, the tax authority may request additions or clarifications.
Important: the 15-day time limit is a forfeiture deadline. Failure to observe it may render the transfer unenforceable against the tax authority, with all the consequences that flow from this.
Step 6: Tax analysis, the tax clearance certificate and the provision of security
The registration of the notification triggers an analysis of the company's tax position. Within 3 working days of the filing of the notification, the central tax authority issues a tax clearance certificate, which is communicated, as the case may be, to the company, the transferor or the transferee. The certificate shows the outstanding tax liabilities and the other budgetary claims established in enforceable titles, outstanding on the date of issue.
– If the CAF shows no outstanding liabilities, the security requirement is deemed to be met — no security needs to be provided.
– If the CAF shows outstanding liabilities, the company or the transferee must provide security covering their full amount, unless the debts have been settled in the meantime.
This is the turning point of the new procedure. The Order limits the acceptable forms of security to those provided for in Article 211(a) and/or (b) of the Tax Procedure Code:
– Deposit of funds at the disposal of the tax authority;
– A letter of guarantee issued by a credit institution or a surety insurance policy issued by an insurance company.
Mortgages and personal guarantees (suretyship) are not accepted in this procedure. Proof that the security has been provided must be filed in original with the tax authority responsible for administering the company's liabilities. The security is administered exclusively by ANAF and is maintained until the liabilities shown in the certificate have been settled in full.
Step 7: Filing the complete application with ONRC
The application to register the filing regarding the transfer of shares must include:
– The application for registration of amendments (ONRC form);
– The GMS resolution / Decision of the sole shareholder;
– The transfer agreement (in original or certified copy);
– The updated Articles of Association;
– Proof that the notification was filed with ANAF (registration number, acknowledgement of receipt or SPV receipt);
– Proof that security has been provided (if the CAF shows debts);
– Copies of the identity documents of the transferor and transferee;
– The transferee's declaration of non-incompatibility (if a new shareholder, in authenticated form);
– Proof of payment of the ONRC fees.
Step 8: The tax check at the ONRC — the certificate requested by the Trade Register
Upon registration of the transfer, the ONRC asks ANAF to issue the tax clearance certificate under Article 701 of the Tax Procedure Code. That certificate contains a statement that ANAF has been notified under Article V of Law No 239/2025 and, if there are debts, the tax authority's consent to the security provided. A certificate issued for this purpose is not subject to extrajudicial stamp duty.
If new debts arise between the date on which the security was provided and the date on which the certificate requested by the ONRC is issued, the company or the transferee must either increase the security or pay the new debts. The ONRC grants, by interim decision, a single deadline for completing the documentation.
Step 9: Deciding the application and registering the filing
After receiving the CAF and checking that the application is compliant, the ONRC registrar issues a resolution:
– Granting the application — if ANAF has been notified and the CAF shows no debts (in which case ANAF's consent regarding security is not required) or contains ANAF's consent to the security provided;
– Rejecting the application — if the ANAF notification is missing, if there are debts without security accepted by ANAF, if the single deadline for completing the file has not been used, or if the file is incomplete;
– Granting a deadline for completion — only once, in order to increase the security or pay the new debts.
The time taken to decide the application depends on the completeness of the file and on how promptly ANAF responds to the ONRC's request.
Step 10: The 60-day deadline for settling the debts — enforcement of the security
For companies that have provided security, the law sets a period of 60 days from the date on which the transfer is registered in the Trade Register for settling the liabilities shown in the tax clearance certificate. According to the Order, this period is mandatory and cannot be suspended or extended by agreement of the parties.
If the liabilities are not paid within this period:
– ANAF realises the security through its enforcement department, without any further prior formalities;
– The person who provided the security (usually the transferee) loses the deposited funds or bears the enforcement of the letter of guarantee/insurance policy;
– As between transferor and transferee, the final allocation of the loss is determined by the transfer agreement.
If the debts are settled in full, the security is released by an administrative act issued by the tax authority and communicated to the persons concerned.
applies in concrete situations
Case 1: Selling an SRL with no tax debts to a third party
This is the simplest scenario. The steps are:
– The transferor and transferee conclude the transfer agreement;
– The GMS resolution is drafted;
– The Articles of Association are updated;
– The notification is filed with ANAF on the standard form within 15 days;
– ANAF issues the CAF within 3 working days, showing no debts — no security is required;
– The file is submitted to the ONRC, which obtains the CAF and registers the entry.
Estimated time: approximately 5–10 working days.
Case 2: Selling an SRL with modest tax debts (under 5,000 lei)
In this case:
– The parties carry out tax due diligence before signing;
– They decide on the solution: either the transferor pays the debts before the transfer (recommended — once the debts are settled, no security is required), or the transferee takes over the liability with a corresponding reduction in the price;
– If the debts remain, the company or the transferee deposits the amount corresponding to the debt and files the original proof with ANAF;
– After registration with the ONRC, the debts must be settled within 60 days;
– ANAF releases the security (if the debts have been settled) or realises it.
Case 3: Selling an SRL with substantial tax debts
For significant debts (for example, over 50,000 lei), the recommended strategy is:
– Negotiating a payment instalment arrangement with ANAF before the transfer, or settling the debts out of the transfer price;
– Obtaining a bank letter of guarantee or a surety insurance policy covering the debt — a mortgage over real estate is not accepted in this procedure;
– Clearly setting out in the transfer agreement the parties' responsibilities for paying the debts and for the risk of the security being enforced;
– Possibly reducing the transfer price by the value of the debts taken over.
In complex cases, the option of reorganising or dividing the company may be more advantageous than a simple transfer.
Case 4: Withdrawal of a minority shareholder from an SRL
The withdrawal of a minority shareholder (for example, one holding 10% of the shares) has also been subject to tax control since 9 March 2026. The procedure is the same — notification to ANAF on the standard form, CAF, security (if there are debts) — even if the withdrawing shareholder did not control the company.
taxation of gains in 2026
In addition to the procedural aspects, the transfer of shares gives rise to tax obligations for the transferor.
For an individual transferor
From 1 January 2026, the gain obtained from transferring shares in an unlisted company is taxed at a rate of 16% (previously 10%). This increased rate applies regardless of the holding period of the shares.
The gain is calculated as the difference between the transfer price and the acquisition value (or the nominal value, if the transferor is the original shareholder).
CASS (the health insurance contribution) may be due, in certain conditions, if the income from the transfer exceeds certain ceilings set by the Tax Code.
The reporting obligations fall on the transferor through the Single Tax Return (Form 212), filed by the standard deadline of the following year.
For a legal-entity transferor
Where the shares are transferred by a legal entity (for example, a holding company selling its participation in an SRL), the gain forms part of the taxable base for corporate income tax (16%), subject to any applicable exemptions for qualifying holdings.
These tax rules are complex and depend on the specific structure of the transaction. We recommend consulting a tax specialist to optimise the operation.
1. Failure to observe the 15-day deadline for notifying ANAF — an error that renders the transfer unenforceable;
2. Notifying ANAF before concluding the transfer agreement — the time limit runs from the actual date of the transfer, not from the intention;
3. Notification without the standard form or without the annexes — the notification must be made on the form approved by Order No 1.137/1.967/C/2026, accompanied by the agreement and the updated articles of association, and proof of filing must be attached to the ONRC file;
4. Underestimating tax debts — seemingly “small” amounts (penalties, interest, fines under enforcement) appear in the CAF and may block the file if no security is provided;
5. Offering a mortgage or a personal guarantee as security — only deposited funds and a letter of guarantee/surety insurance policy are accepted in this procedure;
6. Ignoring the 60-day period for settling the debts — the period is mandatory, and missing it leads to the security being realised without further formalities;
7. An incomplete general meeting resolution — the mandatory statements approving the transfer and updating the shareholding structure are missing;
8. The transferee fails to file the declaration of non-incompatibility when becoming a new shareholder;
9. Failure to check tax debts before signing — the buyer discovers hidden debts after the transfer;
10. A transfer agreement without representations and warranties — leaves the transferee without contractual remedies in the event of hidden liabilities.
What exactly does "enforceability of the transfer against the tax authority" mean?
Enforceability means that the legal effects of the transfer (the transfer of rights and obligations) are recognised by ANAF. If the transfer is not enforceable, ANAF may consider that the transferor remains, for tax purposes, a shareholder of the company and may hold them liable for tax obligations arising after the transfer.
If the company has no debts to ANAF, do I still have to notify the transfer?
Yes, it is mandatory. Notifying ANAF within 15 days, on the standard form, is a general obligation, regardless of whether or not the company has tax debts. The absence of debts only exempts you from providing security, not from notification.
How long does the entire transfer procedure take in 2026?
ANAF must issue the tax clearance certificate within 3 working days of the notification. For a complete file with no tax debts, the whole procedure usually takes 5–10 working days. If there are debts and security is required, it may take 3–4 weeks.
Who provides the security — the transferor or the transferee?
Under Order No 1.137/1.967/C/2026, security is provided by the company or the transferee. The parties may agree in the transfer agreement who ultimately bears its cost — for example, through a price reduction or by the transferor paying the debts before the transfer.
What forms of security does ANAF accept?
Only those provided for in Article 211(a) and (b) of the Tax Procedure Code: a deposit of funds and a bank letter of guarantee or surety insurance policy. Mortgages and personal guarantees are not accepted in this procedure.
What happens if new debts arise after the security has been provided?
The company or the transferee must increase the security or pay the new debts. The ONRC grants, by interim decision, a single deadline for completing the file, after which it requests the tax clearance certificate again.
Can I sell an SRL that is in insolvency?
The transfer of shares in a company undergoing insolvency proceedings is subject to the special rules of Law no. 85/2014 on insolvency-prevention and insolvency procedures. The operation requires the approval of the judicial administrator or the liquidator, as the case may be, and is very rarely encountered in practice.
If the transfer is between spouses or relatives, do the same rules apply?
Yes. The new rules make no distinction between transfers to third parties, to other shareholders or between family members. The tax filter applies uniformly.
What happens if the transferor refuses to notify ANAF?
The notification may be filed by the transferee or by the company (through its legal representative). In practice, any of the interested parties has the right (and the interest) to ensure that notification is made, so that the transfer becomes enforceable for tax purposes.
Can a transfer of shares be annulled afterwards?
Yes, by an action for annulment (under the general law) or by termination of the transfer agreement (for non-performance of obligations). Also, if the transfer was carried out in fraud of creditors, they may bring the actio pauliana (revocatory action) under Article 1562 et seq. of the Civil Code.
Is there any exemption from notification for small SRLs?
No. All limited liability companies, regardless of turnover or number of shareholders, are subject to the same regime.
A transfer carried out in breach of the procedure under Law No 239/2025, GEO No 13/2026 and Order No 1.137/1.967/C/2026 may result in:
– Unenforceability against ANAF — the transferor remains, for tax purposes, a shareholder of the company, with all the obligations that entails;
– Rejection of the registration application by the ONRC — if the ANAF notification or the security for the debts shown in the CAF is missing;
– Realisation of the security by ANAF, if the debts are not settled within 60 days of the registration of the transfer;
– Joint and several liability of the transferor for the company's tax debts, in certain conditions;
– Initiation of proceedings to establish the personal liability of the director, under Article 169 of Law no. 85/2014;
– Tax inactivity declared by ANAF, with the associated consequences (loss of the VAT number, blocking of the bank account, etc.);
– Contractual liability between the parties, on the basis of the representations and warranties clauses.
specialising in commercial law recommended?
Under the 2026 regime, the transfer of shares is no longer a routine operation. It involves the intersection of company law, tax law, ONRC procedure and contract law. A single overlooked element — a missed deadline, an absent contractual clause, an undervalued security — can turn a seemingly simple transaction into lengthy litigation with significant financial losses.
Our firm, based in Târgu Mureș, assists legal entities at every stage of a transfer of shares:
– Full legal and tax due diligence of the target company;
– Negotiating and drafting transfer agreements with protective clauses for both parties;
– Assistance in structuring the transaction optimally from a tax standpoint;
– Representation in dealings with ANAF and ONRC — filing notifications, obtaining the CAF, providing security;
– Resolving procedural blockages at ONRC or ANAF;
– Representation in litigation subsequent to the transfer (actions for annulment, liability, tax).
For complex B2B transactions — business sales, group restructurings, investor entries — an integrated legal and tax approach makes the difference between a successful transaction and a file with hidden risks.
This article is for information purposes only and does not constitute individual legal advice. For an analysis of your company's specific situation and assistance with the share-transfer procedure, we invite you to contact our firm. The legislative information presented reflects the state of the regulations at the date of writing and may be amended by subsequent legislation.
Author: F.R.I.
Copyright © 2026. All rights reserved.
We use cookies that are strictly necessary for the website to work and, only with your consent, statistics cookies (Google Analytics) that show us how the website is used. You can change your choice at any time under “Cookie settings”.
